
I am on my third All in One loan and love it because I am actively reducing the amount of my loan and paying less intere...
Ji Wei L.
FDIC Insured - Backed by the full faith and credit of the U.S. Government
To log in to your personal or business account, please click “Sign In” and follow the prompts for Farmers Savings Bank account logins.
Traditional loans were designed during the 1930's and focused on getting borrowers into a mortgage. The All In One Loan® is a modernized alternative, designed to get them out.
Traditional mortgages can be slow, inneficient, rigid and expense, even with a low interest rate. That's because they amortize the principal and interest portions of each payment, front-loading them with interest cost. And making extra payments towards principal can add risk by locking up those funds permanently in the home. The All In One Loan® changes all of this by combining home financing and personal banking into one financial tool that uses your income and savings to speed up the mortgage process, lower your cost and keep your money available for everyday use.
Benefits
The All In One Loan® is powered by a first lien, 30-year line of credit, and the banking is powered by a personal checking account. Together, this allows you to use idle income and savings dollars to lower the daily principal balance in which mortgage
interest is calculated, reducing lifetime cost and payments automatically.
It may be a great fit if you:
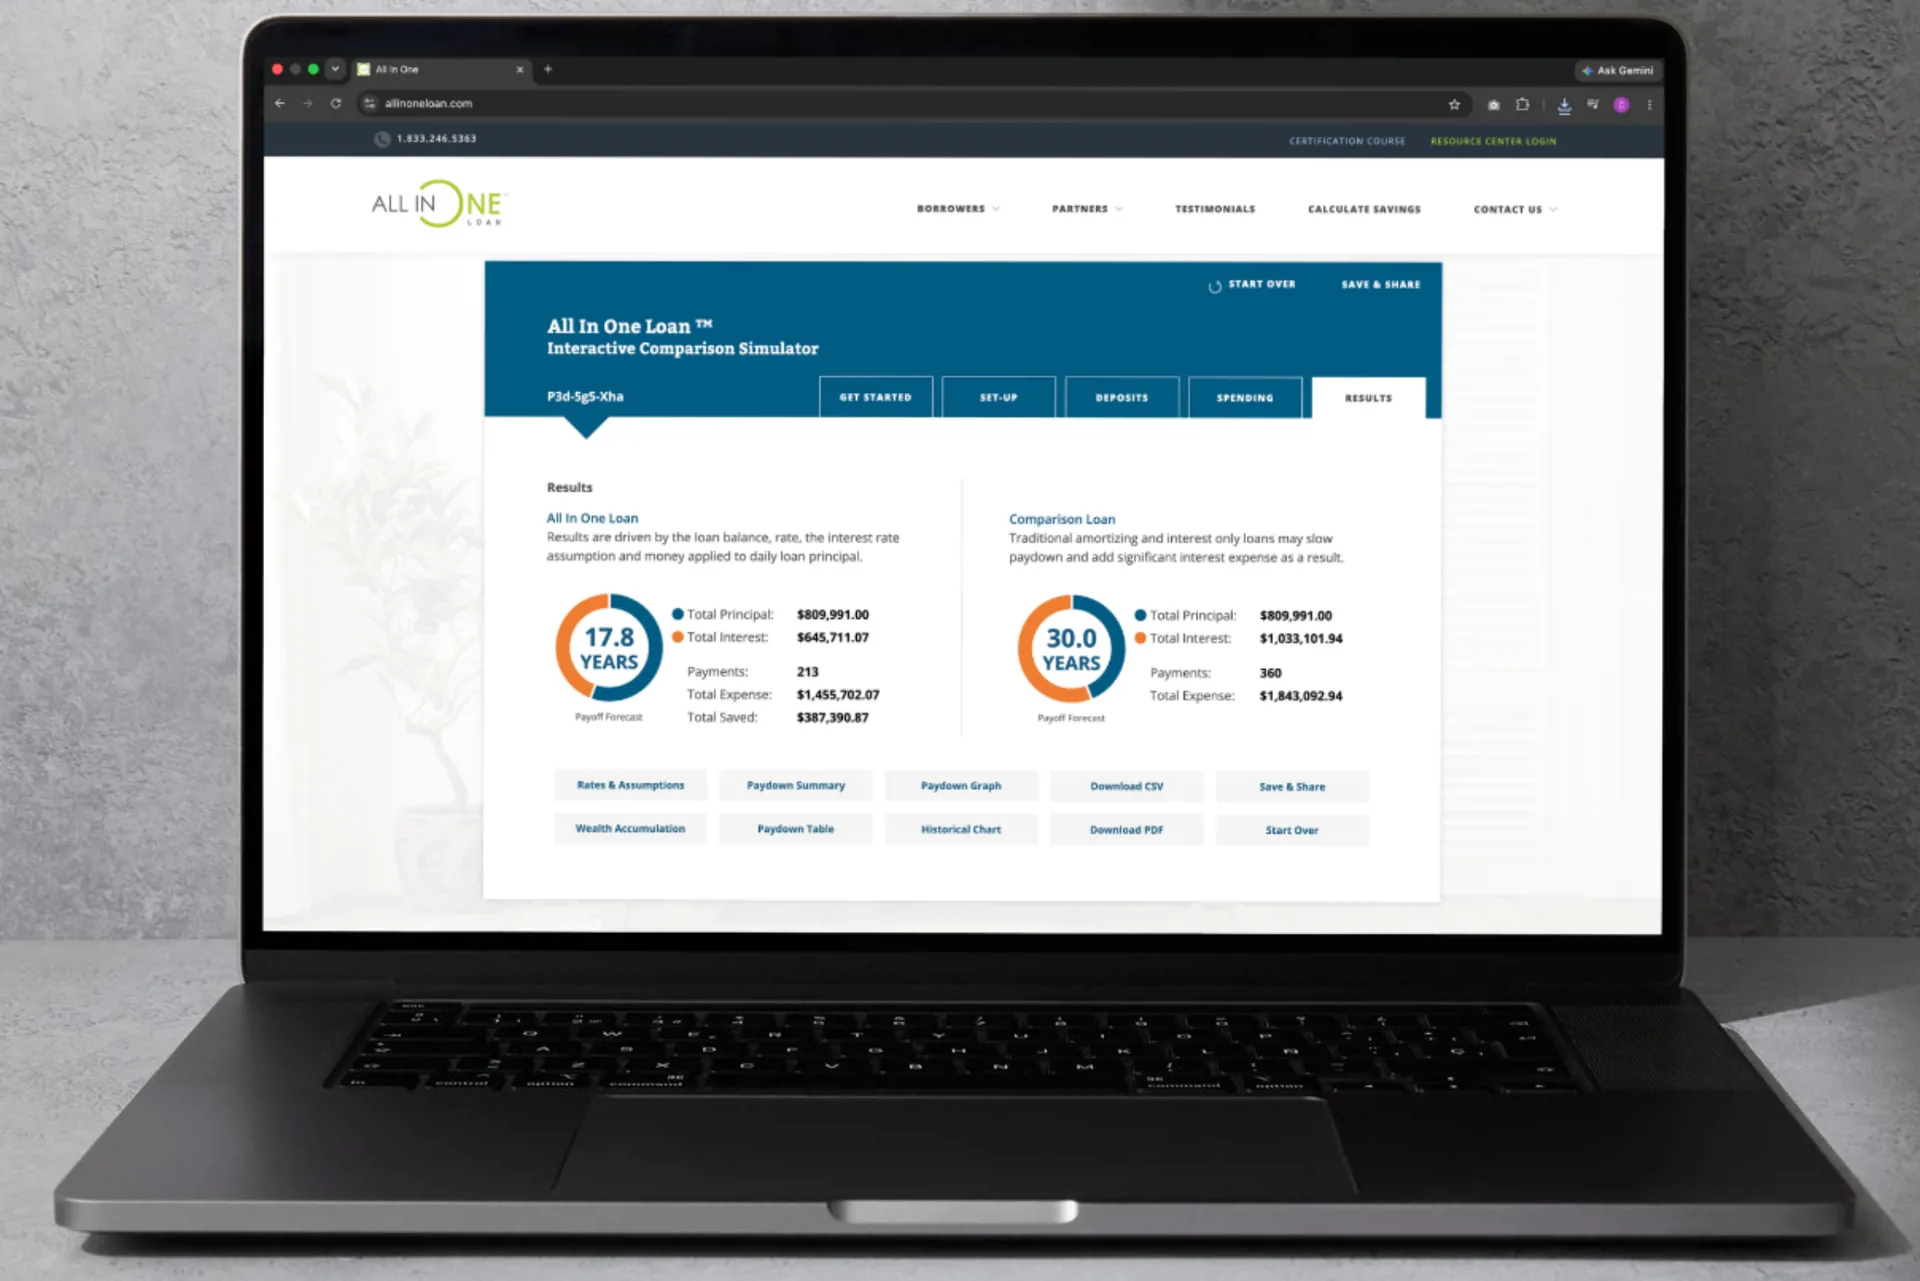
See how your income, savings, and everyday cash flow could work together to reduce interest costs and accelerate your path to mortgage freedom.
I am on my third All in One loan and love it because I am actively reducing the amount of my loan and paying less intere...
Ji Wei L.
I am self-employed. With my income changing month to month I have comfort in knowing I have access to the equity in my h...
Kim.
I hate to get emotional about a financial product but the All In One Loan has changed the trajectory of my family's life...
Jason E.
We've paid off over $40,000 of our home loan with AIO financing in just under 2 years--a dent we definitely wouldn't hav...
Ashley K.
We are estimated to be paid off in 7 years originally. We have paid down by $131,670! I am super excited that we might...
Debra W.
We’re here to help! Find answers to your everyday banking questions.
Yes. The All In One Loan® can be used to purchase a primary residence, second home and investment property, as well as finance the construction of a new customer home.
Yes, the All In One Loan® is available for borrowers to refinance their current mortgage, whether on their primary residence, second home or investment property.
Yes. The All In One Loan® can be used to finance the construction of a new primary or second home, with our convenient one- time close product, allowing borrowers to use their cashflow and savings to aggressively lower their principal balance and interest payments during construction.
Minimum credit score requirements are based on occupancy, loan amount and loan-to-value levels. The minimum credit score for a primary residence or second home up to $2,000,000 at 80% loan-to-value or lower is 700.
Maximum loan amounts are based on occupancy, credit standing and loan-to-value level. The maximum allowable amount for the program is $6,000,000.
The minimum down payment for the All In One Loan® is 10%. Loan-to-value (LTV) limits may differ based on occupancy, loan purpose, and borrower profile.
The maximum debt-to-income ratio for the All In One Loan® is 43%. Debt-to-income requirements depend on several factors, including credit profile, income, assets, and overall loan structure. A loan officer can help evaluate your eligibility.
Yes.
A sweep checking account automatically applies deposited funds toward reducing your loan balance. As money flows into the account, it works against the balance used to calculate interest while remaining available for everyday spending and expenses. *The All In One Loan® does not use a sweep account when applied to primary residences in Texas.
Traditional mortgages typically separate your mortgage from your checking account. The All In One Loan combines home financing, home equity access, and everyday banking into a single platform, allowing idle income and savings to work against your loan balance.
All In One Loan® interest is calculated nightly, after all activity, based on the unpaid principal balance of the loan, by the monthly interest rate (Monthly rate x nightly unpaid principal balance / 365 days = daily interest cost).
Yes. The All In One Loan® checking account is a full-feature, transactional checking account, just like the ones you're accustomed to. It comes with ATM-debit VISA cards, check writing, bill-pay, external account transfers and many more features.
Extra payments made towards a traditional mortgage are locked up permanently, which disincentivizes pre-paying. Borrowers certainly wouldn't pre-pay their mortgage with their paychecks. The All In One Loan® eliminated this issue and
keeps money available for everyday spending needs over the term of the loan.
Yes, that's what it is designed to do. Because money is applied to principal before interest is computed, the balance owed can lower significantly faster. All In One Loan® customers routinely share that their home has been paid off in half the time or less.
Savings vary based on loan amount, income, deposit activity, spending patterns, and other financial factors. Use our propietary Interactive Simulator for a personalized
forecast.
The All In One Loan® is powerful for households with strong positive cash-flow and savings habits, whether a regular wage earner, commissioned or self-employed.
Many self-employed borrowers appreciate the flexibility of a revolving line of credit and the ability to put fluctuating income to work against their loan balance throughout the year.
Traditional mortgages were designed during a bygone era, simply to help more people qualify for mortgage indebtedness. Because the cost of living has risen so significantly since those days, including real estate prices, borrowers have become more dependent on lower interest rate levels for affordability. The All In One Loan® modernizes the approach by allowing income and savings to flow against the debt in which interest is calculated, to drive down monthly payments, lifetime interest cost and the balance, without requiring a refinance once in place, or lower interest rates.
Real stories from real customers.
Check out the unique construction to perm option.