
Property-Specific Financing
Condo Financing
From traditional condominiums to non-warrantable condos, we offer financing solutions that help more buyers purchase the condo that's right for them.
Condo financing that fits your property
Not every condo is financed the same way. Depending on the project, occupancy type, and your financial goals, several financing options may be available. Whether you're buying your primary residence, a vacation home, or an investment property, our condo lending specialists can help you find the financing solution that fits both you and the property.
Condo Financing Options
Traditional condo financing
For condominiums that meet agency guidelines.
- Conventional financing up to 97%
- FHA financing
- VA financing for eligible borrowers
- Jumbo financing up to 95%
- Primary residences, second homes, and eligible investment properties
Condo Financing Options
Non-warrantable condo financing
For condominium projects that don't meet standard agency requirements.
- Financing available for many eligible non-warrantable projects
- Up to 90% financing on eligible purchases
- Available for first-time and repeat home buyers
- May help expand your buying options
What is a non-warrantable condo?
A non-warrantable condo is simply a condominium that doesn't meet one or more of Fannie Mae or Freddie Mac's eligibility requirements. Many non-warrantable condos qualify for specialty financing, helping buyers purchase properties that traditional lenders may not finance.
Examples may include:
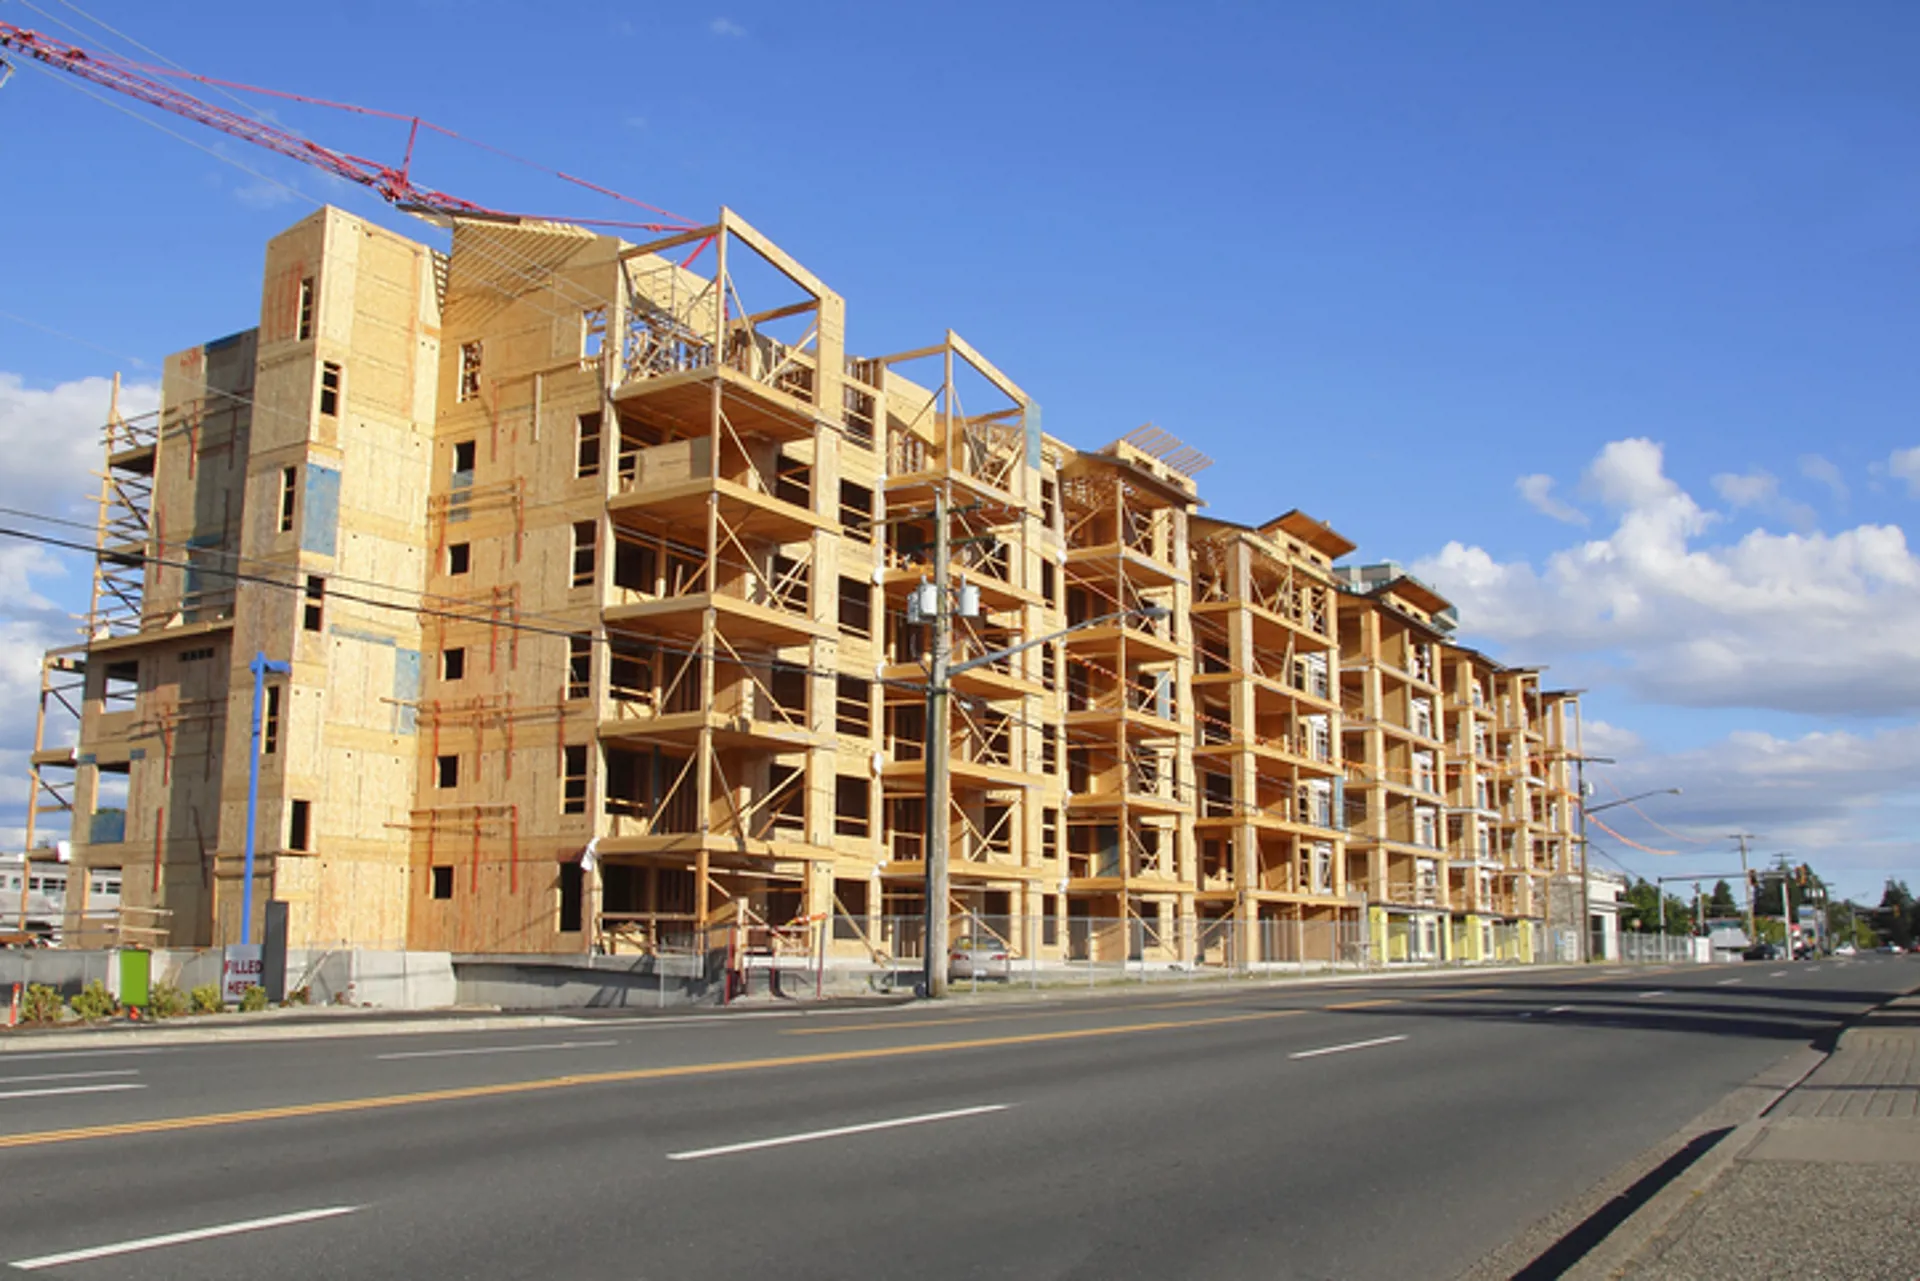
- New construction developments
- Projects with high investor ownership
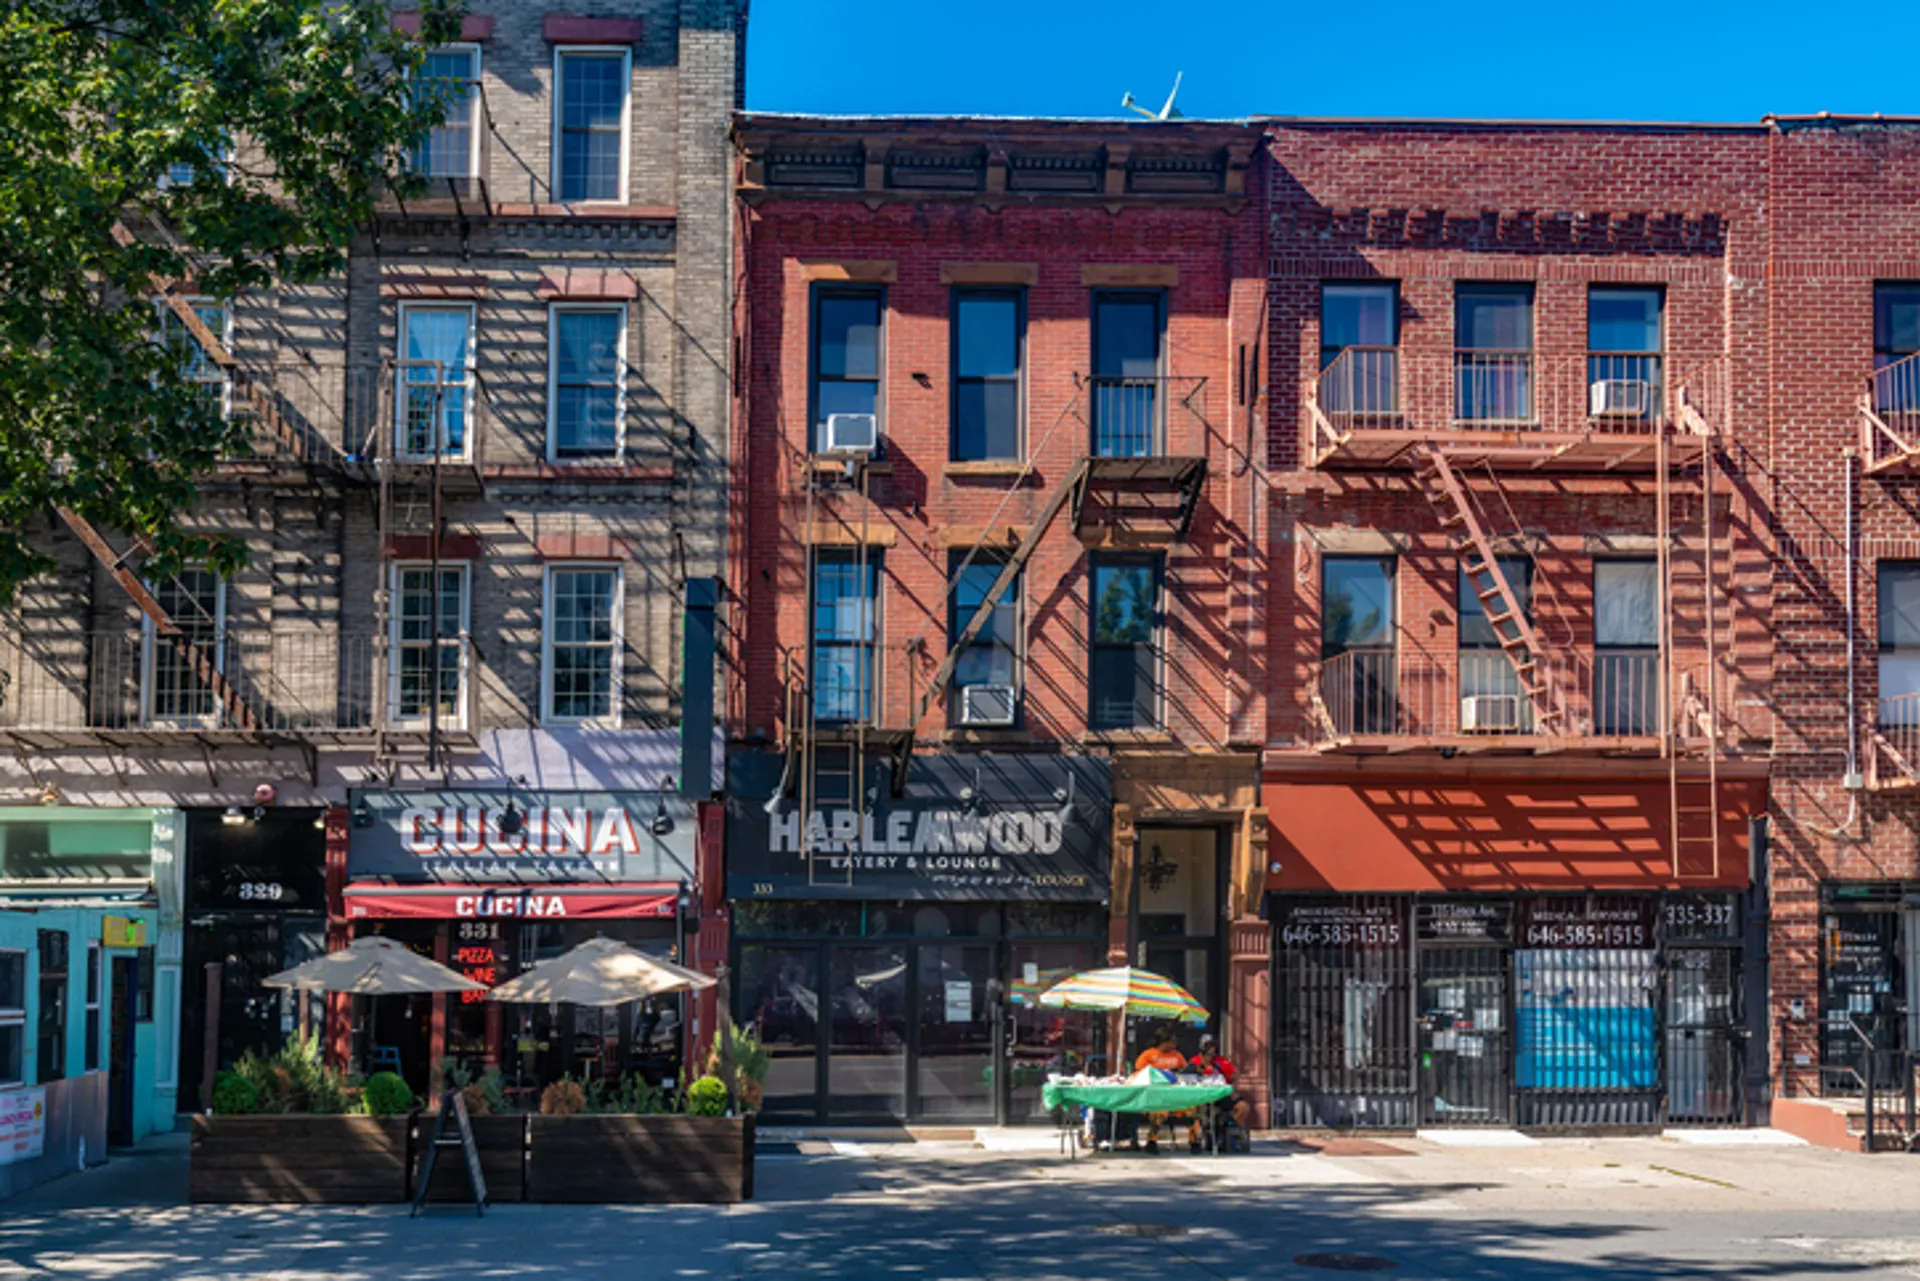
- Mixed-use buildings
- Communities involved in litigation
Why buyers consider non-warrantable condos
Many buyers overlook non-warrantable condos simply because financing can be more specialized. Working with a lender experienced in condo financing may give you access to:
- More available properties
- Less buyer competition
- Potentially better purchase opportunities
- Financing for unique condo communities
- An experienced in-house condo approval team
Our Dedicated In-House Condo Specialists
Not every lender has the experience to finance every condo. Our dedicated in-house condo team specializes in helping buyers navigate complex condo projects, offering in-house FHA approvals and financing solutions for traditional condos, non-warrantable condos, investment properties, and more.
FAQ
Frequently Asked Questions
We’re here to help! Find answers to your everyday banking questions.
A warrantable condo meets the eligibility requirements established by Fannie Mae or Freddie Mac. Your lender will review the condominium project to determine whether it qualifies for traditional financing.
A condo may be considered non-warrantable if it doesn't meet certain agency guidelines. This can happen for a variety of reasons, such as high investor ownership, commercial space within the development, ongoing litigation, or other project-specific characteristics.
Yes. Many first-time home buyers purchase condominiums using Conventional, FHA, or other eligible financing programs. The available loan options depend on the property and your qualifications.
Yes. Financing may be available for eligible second-home condominiums, depending on the project and loan program.
Yes. Eligible investment condominiums may qualify for Conventional, Jumbo, or specialty financing, including financing for some non-warrantable condo projects.
Yes. Depending on the property and your goals, refinance options may be available to lower your rate, change your loan term, or access your home equity through a cash-out refinance.
Not every lender offers financing for every type of condominium. If you've been told a condo isn't financeable, it may still qualify under a different loan program or specialty financing option. Our condo lending specialists can review the project and explore available solutions.
Not always. Down payment requirements vary by loan program and the condominium project. Qualified borrowers may be eligible for low down payment options on many condo purchases.
Resources